Investors who’ve relied on the familiar mix of stocks for growth and bonds for protection might need to rethink both sides of that equation.
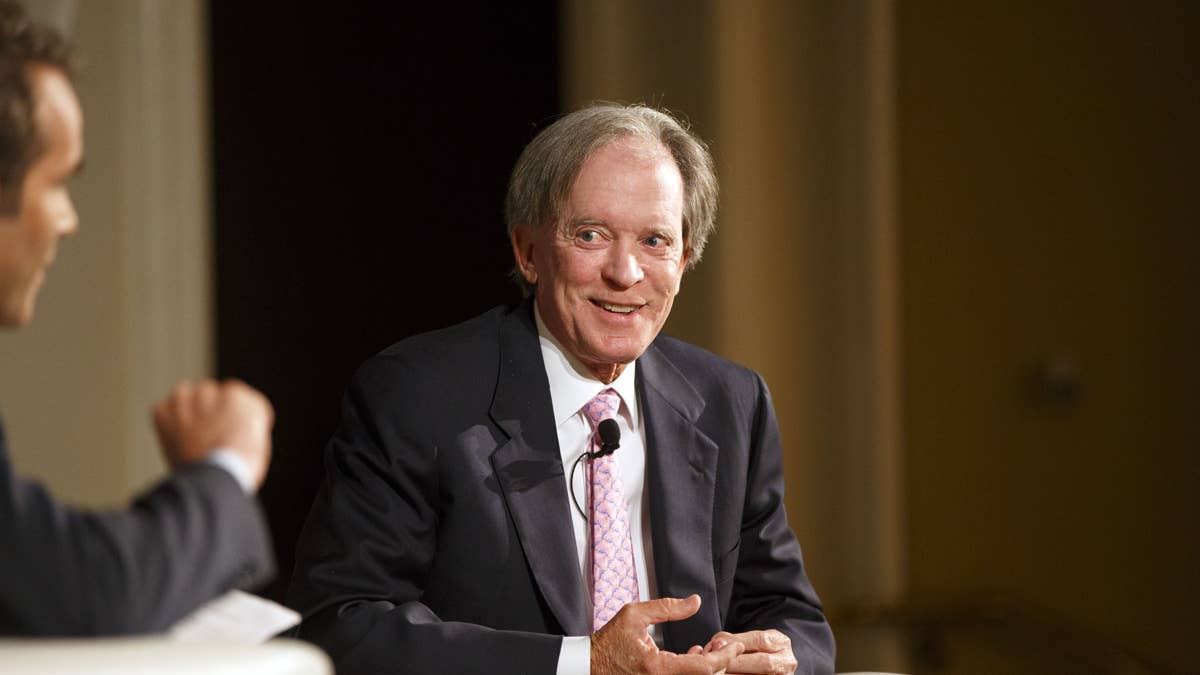
Bill Gross, the legendary investor known as the “Bond King,” warns that persistently high yields could potentially pose a direct problem for stocks by squeezing profit margins and reducing the valuations investors are willing to pay, as reported by Fortune.
It’s a pointed message for shareholders in expensive growth stocks and companies relying heavily on debt.
Gross is not calling for an immediate market collapse, though. His concern is that the financial backdrop itself is changing as government and corporate debt rise, Treasury yields stay elevated, and borrowing costs remain higher for longer.
Why Bill Gross still gets Wall Street’s attention
Gross earned the “Bond King” title as he effectively turned fixed income from a buy-and-hold corner of finance into an actively traded asset class for total return.
He co-founded PIMCO in 1971 and later ran its flagship Total Return Fund, which became the world’s largest bond fund.
Morningstar named him its Fixed-Income Manager of the Decade in 2010, as reported by the Boston Herald, while PIMCO still credits the strategy he pioneered with combining coupon income and capital appreciation rather than simply “clipping coupons.”
Gross has also made multiple prescient calls on traditional bond investing that aged well. In 2007, before the financial crisis fully erupted, he identified collapsing confidence in ratings and structured credit as a mechanism capable of freezing lending markets, Quartz noted.
His more recent energy bet has also paid off. Gross has described a portfolio of pipeline master limited partnerships as one of his best investments, with Western Midstream producing a total return of more than 200% over five years, a Business Insider report confirmed.
Bill Gross sees valuation problem building beneath the stock market
For stock investors, Gross’ warning is essentially that the financial system is carrying far greater debt at a time when that debt has become much more expensive to finance.
U.S. domestic nonfinancial debt reached $84.1 trillion in the second quarter, including $24 trillion owed by businesses and $38.7 trillion by governments. Debt was still growing at an astonishing 5.2% annualized pace.
More Wall Street:
- Wall Street’s AI trade faces its biggest valuation test
- The next Wall Street shift is already underway
- Wall Street sends strong 4-word verdict on the stock market
Gross’ concern is that borrowing can support growth and asset prices for a while, but eventually the bill shows up through higher interest expense, persistent inflation, and tighter financial conditions.
The AI boom adds another layer. He has pointed to roughly $1 trillion of debt-financed AI investment by 2027, while AI-linked hyperscalers now represent about 16% of the U.S. investment-grade bond market.
For me, that is where this stops being a bond story and becomes a stock-market story.
The 10-year Treasury yield recently reached 5.34%, its highest level since 2002, as reported by Reuters. Gross argues that “higher yields over time will contract profit margins,” and I think that risk works through stocks in two ways.
First, companies paying more to borrow have less room for investment, buybacks, and earnings growth. Second, investors no longer need to accept the same valuation risk when government bonds offer yields above 5%.
The S&P 500 is near record territory, trading at around 19.2 times forward earnings, according to Reuters. The multiple has already compressed from roughly 22 earlier this year, but elevated yields still raise the hurdle for expensive stocks.
I would not read Gross as predicting an imminent crash.
Even if earnings keep growing, stock prices can struggle if investors decide those earnings deserve a lower multiple in a world of persistently high yields.
What Gross wants investors to do now
Gross’ investment philosophy can be effectively condensed into four words: “Preserve and protect.”
He is unusually defensive across both major asset classes.
On bonds, Gross advises avoiding longer-term debt and makes an exception for one-year Treasury bills yielding around 4.55%. Investors can collect meaningful income without taking the same price risk that comes with owning a 10- or 30-year bond if yields move higher again.
On stocks, he is not saying investors should liquidate everything.
His objection is primarily to paying aggressive valuations while financing costs remain high. Gross says he is suspicious of AI hyperscalers unless their P/E ratios fall below roughly 20 times earnings.
So what he’s calling for is for investors to demand more compensation for risk.
A company financing growth at 3% rates can justify a different valuation than one refinancing debt at 6%. Similarly, a 35-times-earnings stock has a higher hurdle to clear when short-term government securities yield more than 4% and the 10-year Treasury yields more than 5%.
Gross also points toward income-producing securities trading at discounts to net asset value, although he warns that those can suffer if short-term rates rise further.
He mentions Verizon (VZ) and AT&T (T) as examples of stocks with strong yields, while simultaneously flagging the competitive threat Starlink could pose to their businesses.
At the same time, the counterargument is substantial.
S&P 500 profits are still growing rapidly, AI investment continues to support economic activity, and some strategists are already discussing an S&P 500 at 10,000 later this decade.
Gross is questioning what would happen if the bond market refused to cooperate with that bullish story. With federal debt held by the public already around 101% of GDP and the CBO projecting it to reach 120% by 2036, elevated high yields could turn what looks like an earnings story today into a financing and valuation problem tomorrow.
Related: Nvidia’s AI boom revives a Warren Buffett warning for investors