Most of us know Venmo as the app we open after dinner with friends. Someone covers the check, and everyone else pays them back from their phone.
But the person on the other end of the payment is changing, as Venmo is gaining massive traction among businesses.
I’ve covered retail and restaurants for more than a decade, and I rarely see a payment habit jump from the friend group to the cash register this fast.
Also Read: Michael Burry takes money off the table after stock nearly doubles
Venmo for business is growing fast
In the Q3 earnings call, PayPal, Venmo’s owner, said Venmo’s total payment volume has grown at a double-digit rate for eight straight quarters.
CFO Jamie Miller said Pay with Venmo, which lets shoppers pay merchants through the app, grew 43%.
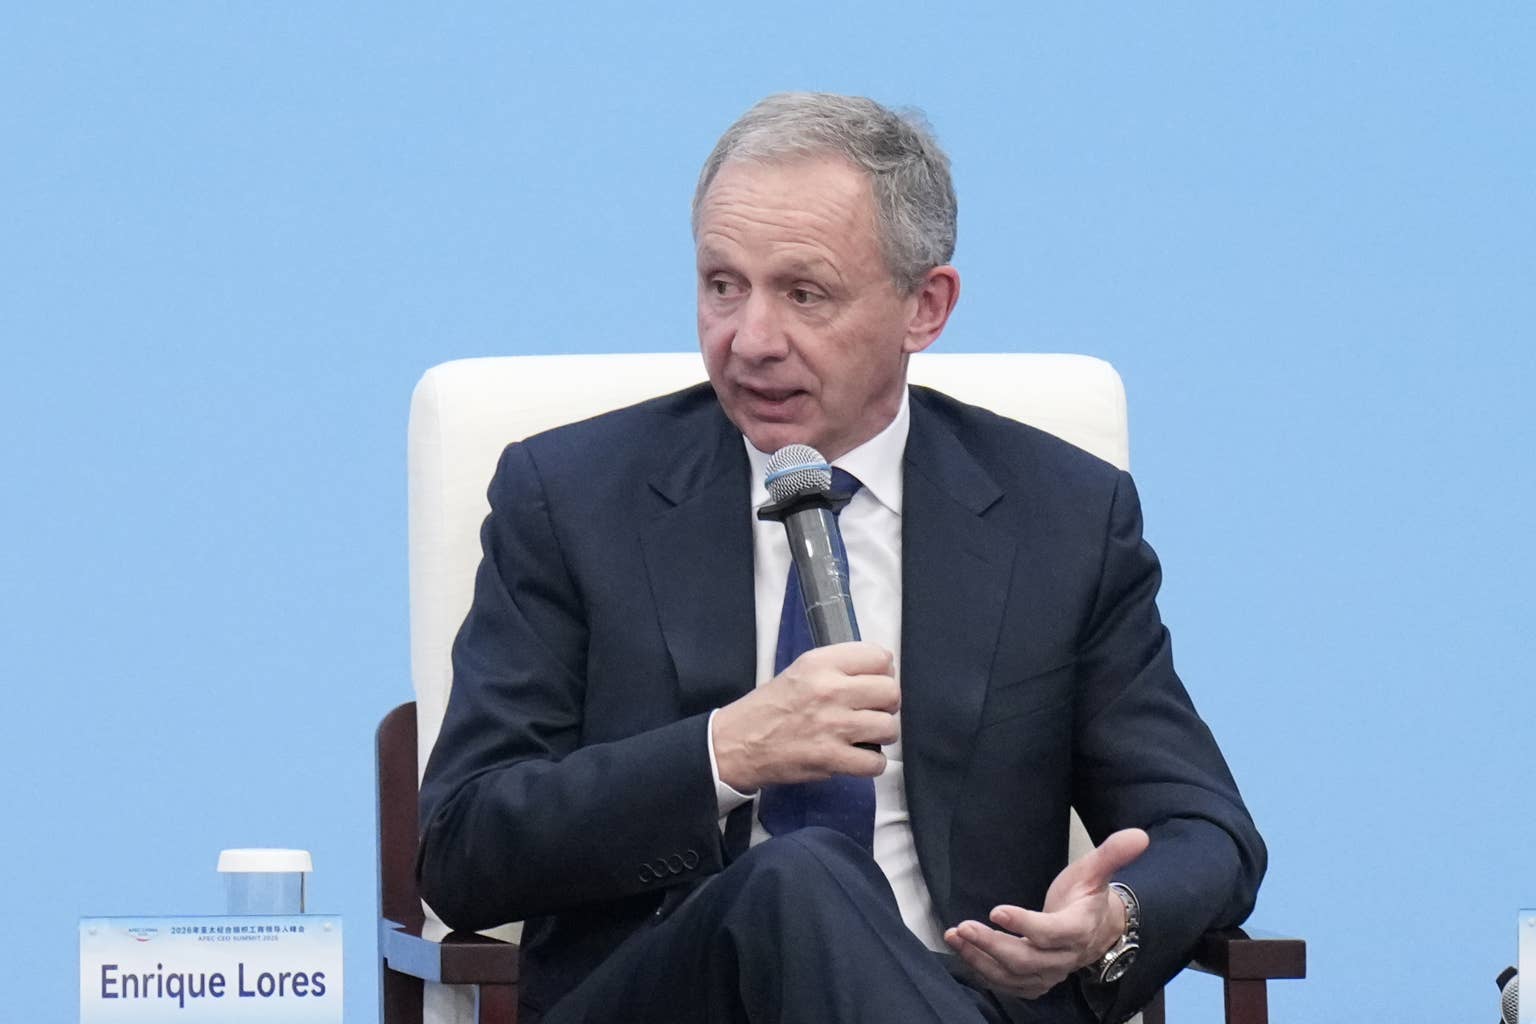
“We are seeing also very good progress on Pay with Venmo, and Pay with Venmo TPV grew more than 40% this quarter,” CEO Enrique Lores emphasized. “So the growth in the future will be driven by continuing to drive these areas, and we expect to continue to see double-digit TPV growth for Venmo in the coming years.”
More Tech:
- Apple CEO signals surprising change for iPhone users
- Comcast sends wake-up call to employees as customers cut services
- AI agents’ growing role in payments raises an awkward question
A business profile takes minutes to set up and has no monthly fee, while one industry review estimates more than two million merchants now accept Venmo.
The businesses leaning in include stylists, dog walkers, lawn crews, tutors, food trucks, and craft fair vendors. For them, a card reader and a merchant contract can feel like overkill.
Venmo asks for neither. A profile, a QR code, and a customer who already has the app are enough.
Miller said at the KBW Fintech Ecosystem Conference on Nov. 10 that Venmo has 70 million consumers, largely young and affluent.
The fee math on a $10 latte
Here’s how Venmo generates revenue:
- Venmo charges business profiles 1.9% plus 10 cents per payment and 2.29% plus 10 cents for tap-to-pay.
- On a $10 latte, the fee is about 29 cents. The shop keeps $9.71. That’s roughly 3% of the sale, and notably, Venmo doesn’t refund seller fees.
- Standard bank transfers take one to three days and cost nothing, while instant transfers cost 1.75%, with a 25-cent minimum, which is expensive.
While Fees are predictable, fraud isn’t. Several articles have cited security researchers who describe overpayment schemes and fake payment receipts aimed at business accounts.
Funds can be pulled back out of a seller’s account once fraud is detected. By then the goods are gone, and the owner is left with no product and no money.
In addition, under last year’s tax law, the reporting threshold for payment apps went back to $20,000 and 200 transactions, so fewer owners will receive a tax form. That doesn’t make the income less taxable.
Without a form, owners need to maintain their own records, and mixing personal and business payments makes that harder.
What PayPal really wants
PayPal (PYPL) management said online branded checkout volume has grown just 1% to 2% for four straight quarters.
However, Venmo is expected to be a key growth driver and could surpass $2 billion in revenue next year, according to estimates outlined in 2025.
Lores sees plenty of room for growth.
Related: Down 82% from all-time highs, can PayPal stock finally recover in 2027?
He said only 23% of Venmo customers use any of the company’s financial services today, and he sees a four- to five-times opportunity to raise revenue per active account.
Miller, speaking at the KBW Fintech Ecosystem Conference on Nov. 10, identified who the next customers might be.
She described the opportunity as “looking at micro sellers and sole proprietors around different kinds of credit products that help them manage their business better or manage their cash flow better.”
However, Venmo faces competition from low-cost peers.
For instance, Zelle charges small businesses nothing to receive money, according to NerdWallet.
My take on Venmo at the register
Venmo is a great way for a small shop to start taking payments. It doesn’t replace the tools that back up a sale, such as dispute handling, receipts, and clean records.
And the vendor taking Venmo at the farmers market today is the customer PayPal hopes to sell credit to tomorrow.
Given consensus estimates from TIKR, Wall Street forecasts revenue to increase from $33.17 billion in 2025 to $42 billion in 2030. Over this period, adjusted earnings could expand from $5.31 per share to $9.11 per share.
These estimates could move higher if Venmo continues to gain significant traction among users and businesses.